1.0 Introduction
The Australian housing business stands in the centre of the Australian economy because its existence can define people's dependence on wealth, consumption and compared investments. Sydney, Melbourne and Brisbane are the 3 best capital cities market illustrating the most influential market in this industry in the package presented by the relevant demographic, economic and the policy aspects. The second-largest city, Melbourne, is historically among the most significant beneficial languages of the growth of population, as international and interstate migration indicate. Finally, Brisbane, the largest city in Queensland has emerged as a viable alternative to the relatively affordable southern capitals, and IS is cashing in on the elements of interstate migrations in inflows.
In this report, the author examines a price trend of a house in these three cities in 2015 and in June 2025 and projections have been made in 2026 and 2027. Detached residential houses and not apartments and commercial property are only considered in order to assure a coherent base of analysis, and to uncover the property underwriting of the universe of urban housing markets. This analysis would aim at trying to realise long-run variation and elucidate by the reasons of the realised fluctuations, not to give predictions but to simply take rational assumptions.
Students seeking academic guidance on business, economics and market analysis topics can explore our Best Assignment Help Australia services.
2.0 Historical Price Change (2015–2025)
(Source: Self-Created)
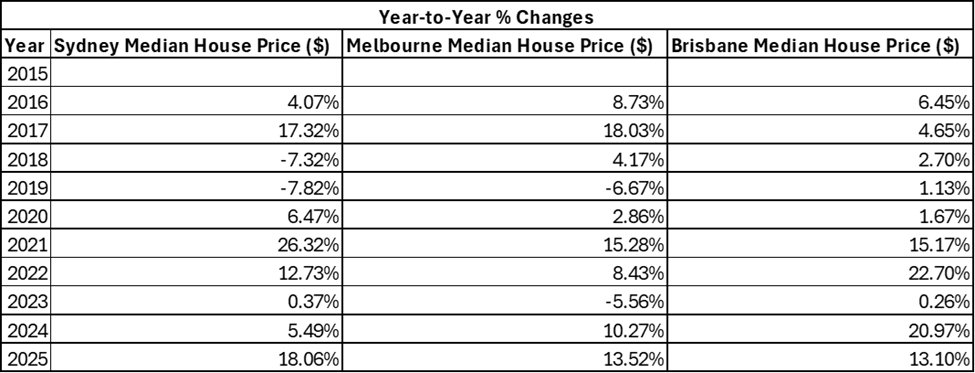
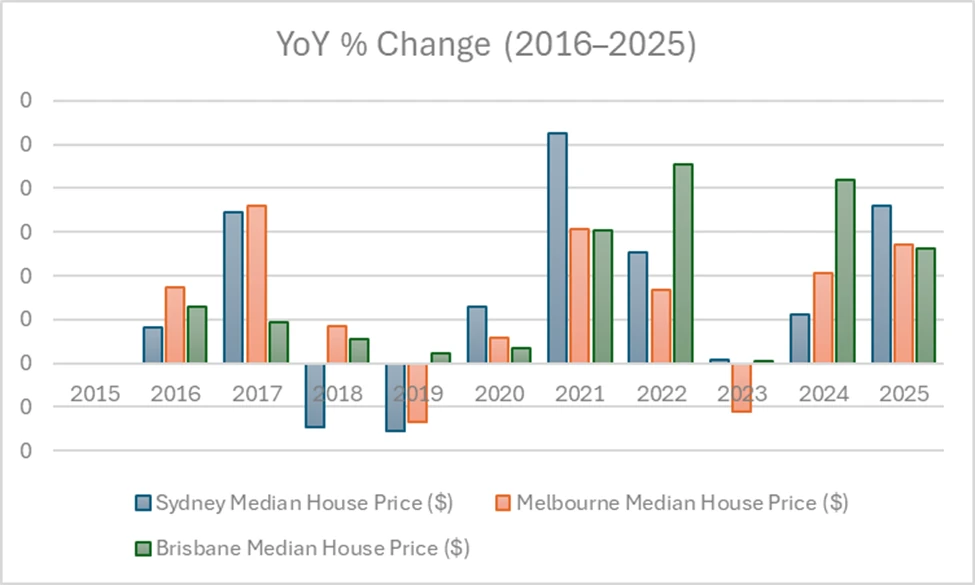
The median price of houses in the period between 2015 and June 2025 witnessed a major increment in all the regions surrounding Sydney, Melbourne and Brisbane. Sydney per capita growth increased by 97.7% to 1700000 people in the year 2025 from 860,000 people in 2015. In the same period, the Melbourne growth was 89.7% in the sense that it increased Melbourne to 561000 to one-trillion reported by 1064000 (Khanjanasthiti et al., 2025). The highest%age of change was registered in Brisbane at 128.0% because the number has significantly grown and is projected to reach 1060311 dollars in 2025 after registering the $465000 in 2015.
(Source: Self-Created)
Sydney
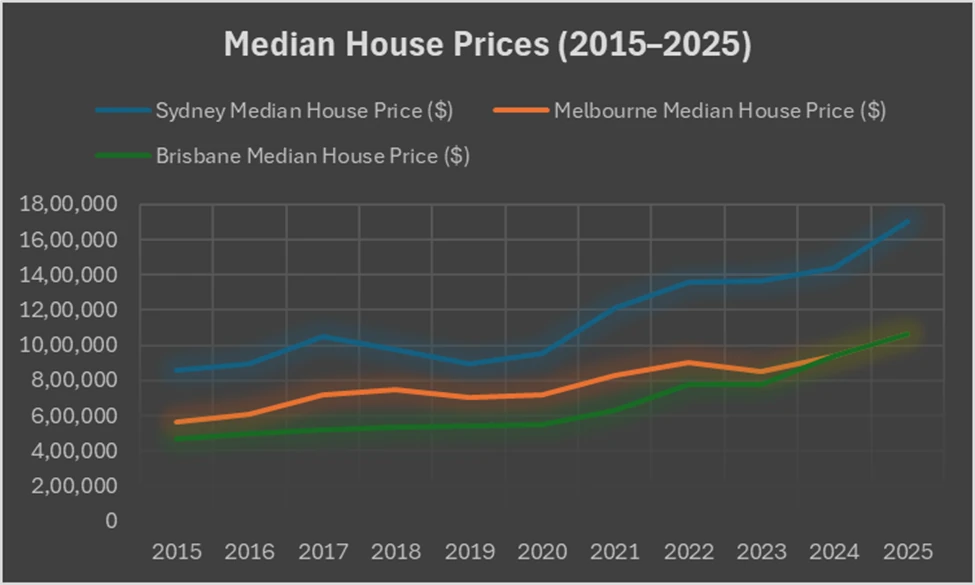
The fluctuation of the character of Sydney was heavily tinged. The prices have increased over 17% in one year between 2015 and 2017 due to the lowest interest rates in history, strong foreign investment and low availability of the desired suburbs. This is however corrected in the year 2018 and 2019 with settlement: -7.3 and -7.8 respectively year-on-year reductions. Lending restrictions and tightening of credit would then be the great contribution towards this decline (Glackin et al., 2025). The recovery followed with an intensive recovery as the 2020-2021 period witnessed a significant growth in prices stimulated by an immensely low rate of interest and massive household savings during the pandemic. Annual growth reached 26.3% in 2021. Sydney reached a high of $1,360 000 as of 2022 but the affordability aspect and rate of increasing interest in 2022-2023 put a check on the increase, with growth in 2023 only by 0.37%. The median of its price of one point seven billion would result in the recovery restoration in 2024-2025.
Melbourne
The Melbourne city registered a stable growth in the initial reading in the 10 year period. This increased the prices to encompass a level of 750,000 in 2018 as compared to the earlier price of 561,000 in 2015. Growth on the other hand slowed down in 2019, negatively with -6.7 growth, which was due to the changes in the regulations and affordability. In 2020, the city has recovered averagely and entered the high-growth in 2021 averagely, at $830,000 (Vichiensan et al., 2023). Lockdown and emigration were also a problem, contributing to the phenomenon a worse impact on Melbourne than on other cities like Sydney and Brisbane because it created pressure on demand to live in the inner city neighbourhoods. As a result, in 2021/2022, Melbourne is relatively growing less acutely as compared to Sydney and the growth rate in 2022 is 8.4% as compared to 12.7% in Sydney.
Brisbane
The Brisbane trend showed a steady movement in particular, the second half price. This shows that the prices had incrementally increased with a decrease of only 32 years between 2015 and 2020, 465,000-547,000. Following slowed growth in 2021, increase in interstate migration reported 15.2%, then jumped to 22.7% in 2021 and 2022 respectively as a result of growth in interstate migration, with the southern capitals making its perception relatively affordable, and more investment in infrastructure (Pradhan, 2025). Brisbane reached its peak of 773,000 in 2022 and its peak continued to rise in 2022 and 2024, to 1,060 311, respectively.
Students working on property market analysis, housing trends and real estate topics can explore our Real Estate Assignment Help for academic writing guidance and support with their assignments.
3.0 Expected Price Change (2026–2027)

(Source: Self-Created)
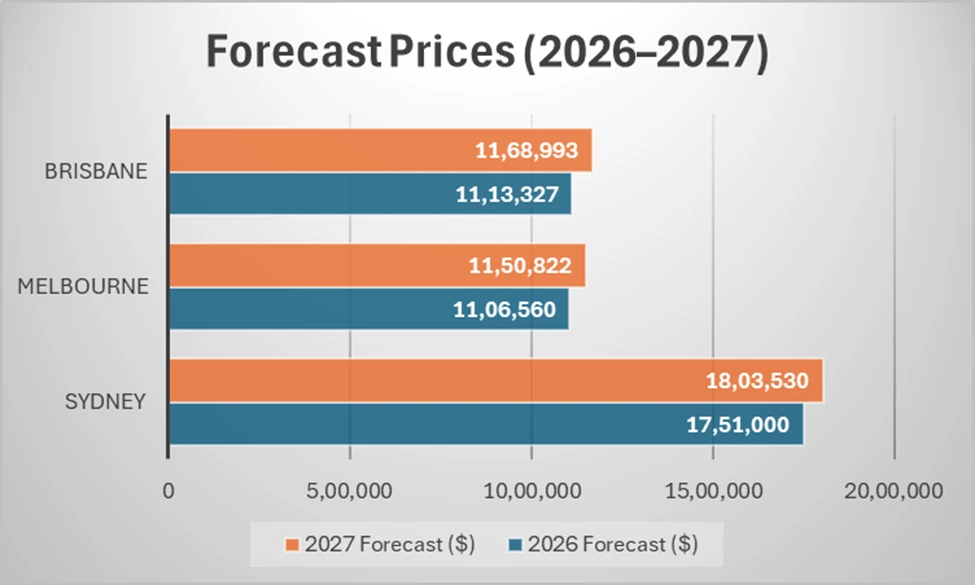
The preceding forecasts up to 2026 and 2027 are based on an explicit growth rate assumption, fitted macroeconomic and demographic and supply-side forecasts. Brisbane, Melbourne and Sydney are alleged to develop into 3 ties, 4 notches and 5 teeth, respectively. These are assumptions of relative affability, the migration patterns and the infrastructural projects (Sobels et al., 2024). Following the utilisation of these rates to 2025 medians, the projection up to 2026 and 2027 would claim 1,751,000 and 1,803,530 more in 2026 and 2027 respectively in Sydney, Melbourne, and Brisbane.
Sydney
The Sydney market would have to maintain the position as the most expensive market but as there will likely be less growth in future. Median household income is the limiting factor to such a major challenge of affordability because the rise in house price is far greater than the household incomes. Social restriction of housing supply under the zoning laws and issues of construction bottlenecks will give the commodity an upward price pressure (Xu et al., 2023). The stable interest rate policy along with no significant growth of French stimulus can be defined as moderate growth and no further increase. Rejuvenation of international migration is anticipated to generate pressure and particularly in the employment centres of high-demand suburbs. With reference to these circumstances, Sydney is likely to grow around 3% annual as compared to 1.8 million in the year 2027.
Melbourne
It has been reported that the recovery in the Housing Market of the city of Melbourne has been consistent as compared to the volatility seen over the last ten years. It is expected that the housing demand will be pegged on the reinstatement of robust population growth that may be caused by the factors of international and interstate migration. The unlocking and increased investment in infrastructure of transport and urban renewal will stimulate demand in the suburban housing and increase the final stage housing demand (Buckle et al., 2024). Affordability however is not something in their favour and they can be cheaper than Brisbane, which has restraint to stimulate growth. Supply will also be limited because stalling the price will occur through an upward management in the construction cost. Among these assumptions, there is a projected 4% per annum market increase in Melbourne with an estimated growth as at 2027 to be 1.15 million.
Brisbane
It is foreseen that Brisbane would become more successful in its comparative rise over Sydney and Melbourne thus the existing interstate migration, comparative affordability and the mass infrastructures being developed around the 2032 Olympic Games. The potential of these is to create and sustain a high demand and restrictions set up by the high construction costs and scarce land supply even augment the prices that have already been fixed on houses (Dadpour et al., 2024). Economic sampling across the state enhances the long term demand fundamentals with a boom in the health, technology and educational spheres. Therefore the town of Brisbane is claimed to grow at an approximate rate of 5% per year up to around, inexpensively increasing to near 1.17 million thus diminishing the lead over the cost of Melbourne and establishing its stand as a profitable housing market.
It is assumed that Sydney will remain the most costly town to the locals in 2027 yet Brisbane will be anticipated to reduce the comparative distance to Melbourne (Preeti et al., 2022). Simultaneously, with the constraint on the growth of Sydney due to the affordability, and Melbourne due to the oscillation of migration dynamics, Brisbane growth is benefited through the infrastructure and the inter-state migration factor.
(Source: Self-Created)
4.0 Conclusion
Prices of residential property in Sydney, Melbourne and Brisbane in 2015-2025: the comparison between the cities reflects some national aspects concerning the property market and some local peculiarities. Sydney was the most stable, although significant corrections in 2018-2019 and spectacular growths in 2020-2021 proved to deliver high absolute prices. The migration trends and the oversupply issue dominated the performance of the Melbourne and as a result, underperformance during the post-pandemic period. Brisbane performed the best in comparison with other cities as affordability and infrastructure based demand grew over the period of ten years by 128%.
The three cities are domesticated to prevent a moderate growth by 2026 and 2027. As certain funds would be set aside to recover the migration pace and the infrastructure which had been borrowed assuming the interest rates to be constant, the system projected that Melbourne, Brisbane, and Sydney would develop by 3%, 4%, and 5% annually respectively. These forecasts indicate that Sydney will be the most costly marketplace, and it will be likely to find Brisbane decreasing the distance between itself and Melbourne. The lowered expectations and the greater growth compared to the past decade and affordability, policy and supply remain the key aspects of performance quantification.
Reference List
Journals
- Buckle, C., Werner, G., Marshall, N., Searle, G., Osbaldiston, N., Sarkar, S., Kundu, D. and Gurran, N., 2024. Place-based drivers and effective management of population growth and change in regional Australia. AHURI Final Report, (425).
- Dadpour, R., Law, L. and Osbaldiston, N., 2024. Paradise lost? Rental housing insecurity and the lived experiences of amenity migrants in Cairns, Australia. Australian Planner, 60(1), pp.58-71.
- Glackin, S., Rowley, S., Kollmann, T. and Veeroja, P., 2025. Small-area analysis and projections of social housing change (No. zrgvb_v1). Center for Open Science.
- Khanjanasthiti, I., Bajracharya, B. and O’Hare, D., 2025. Towards More Sustainable Planning Decisions Around Airports: Investigating Global Airport Classifications and Proposing a Four-Tiered System for Australia. Sustainability, 17(12), p.5259.
- Pradhan, S., 2025. Australia's Social and Affordable Housing Crisis and the Role of Community Housing Organisations (Doctoral dissertation, Queensland University of Technology).
- Preeti, P., Haddad, K. and Rahman, A., 2022. Assessing the Impacts of Climate Change on Rainwater Harvesting: A Case Study for Eight Australian Capital Cities. Water 2022, 14, 3123 [online]
- Sobels, J., Cook, P., Kanck, S. and O’Sullivan, J., 2024. Big thirsty Australia. Sustainable Population Australia.
- Vichiensan, V., Wasuntarasook, V., Prakayaphun, T., Kii, M. and Hayashi, Y., 2023. Influence of Urban Railway Network Centrality on Residential Property Values in Bangkok. Sustainability, 15(22), p.16013.
- Xu, R., Yu, P., Liu, Y., Chen, G., Yang, Z., Zhang, Y., Wu, Y., Beggs, P.J., Zhang, Y., Boocock, J. and Ji, F., 2023. Climate change, environmental extremes, and human health in Australia: challenges, adaptation strategies, and policy gaps. The Lancet Regional Health–Western Pacific, 40.